The envelope arrives, and the single sheet of paper inside feels heavier than it should. Your insurance claim, filed so carefully after the storm, fire, or flood, has been denied. It is a gut-punch moment that leaves too many property owners frustrated and uncertain.
You paid your premiums and held up your end of the bargain, only to have the safety net pulled away. What you do next can determine the entire outcome of your recovery.
For homeowners and commercial property owners in Texas and Mississippi, the most effective first step is often hiring a professional advocate. Our Public Adjusters exists to shift the balance of power back to the policyholder.
What is the First Thing I Should Do If My Insurance Claim Is Denied?
It is natural to feel panicked or angry, but a calculated response gets results. Before firing off an emotional email or spending hours on hold, take two strategic steps.
First, if you do not have it already, formally request the insurance claim denial letter in writing. This document is the foundation of your appeal because it forces the insurer to state their exact reasons for the denial, citing specific policy language.
Second, and this is crucial, do not try to negotiate on your own. Contact a licensed public adjuster for a consultation instead. Having an expert review your denial letter and policy is the strongest opening move you can make.
The team at Our Public Adjusters offers a free phone consultation to give you that initial assessment and immediate clarity on your options.
The Critical Difference: Public Adjuster vs. Insurance Adjuster
To protect your financial interests, you have to know who is on your side. Many policyholders assume the adjuster sent by their insurance company is a neutral party, but this is a costly misunderstanding. The two roles are completely opposed:
- Allegiance: The insurance company adjuster works for them. Their professional duty is to protect the company bottom line. A public adjuster, like the team at Our Public Adjusters, is hired by you and represents only your interests. Their sole fiduciary duty is to you.
- Goal: The insurance adjuster job is to assess the claim based on company rules and limit the payout. A public adjuster mission is to document all your damages and secure the maximum insurance settlement allowed by your policy.
- Process Control: If you deal directly with the insurance company, their adjuster controls the timeline, the information, and how the policy is interpreted. A public adjuster takes over the entire claims process for you, from communication and documentation to negotiation.
How Much More Money Do You Get with a Public Adjuster?
The value of expert representation is not just a theory, it shows up in the numbers. While every case is different, data highlighted on the company website referencing historical government findings shows significant differences in recovery. Policyholders who hired public adjusters for hurricane claims received payouts that were, on average, 747% higher than those who went it alone.
Even for non-catastrophic claims, settlements were notably higher. This data shows that a public adjuster does not just manage the process, as they can completely change the financial outcome by leveling the playing field with large insurance companies.
What are Common Reasons for Claim Denials in Texas and Mississippi?
With 17 years of experience serving property owners in Texas (License #1600788 / 1628479) and Mississippi (License #10408934 / 15027825), the team at Our Public Adjusters has seen every denial tactic in the book. As weather in the region becomes more severe, claims only get more complex. Some of the most common reasons for denial are:
- Wear and Tear Exclusions: Insurers often argue that damage, particularly to a roof after a hailstorm, is just pre-existing wear and tear instead of acute storm damage.
- Flood vs. Water Damage Disputes: After a hurricane, carriers might deny a claim by saying the damage was from flooding, which needs separate flood insurance, and not from covered wind-driven rain.
- Insufficient Documentation: Policyholders do not always provide the exhaustive proof of loss that carriers demand, which can lead to underpayments or a flat-out denied insurance claim.
- Late Notice: Policies have strict deadlines for reporting a claim. Miss that window, and you could face an immediate denial, even if the claim is valid.
Navigating these local challenges requires specific expertise. An experienced Texas and Mississippi public adjuster has a major advantage over anyone trying to fight an appeal alone.
The Client Experience: What It Is Like to Work with Our Public Adjusters
The whole point is to take the burden off your shoulders. It starts with a free, no-obligation phone call to go over your property damage claim.
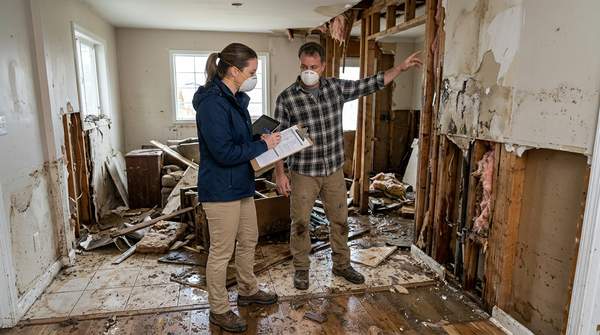
If you decide to move forward, the team, led by principal Richard Myers, takes over everything. They perform a meticulous on-site inspection to document all the damage, dive deep into your insurance policy to find every area of coverage, and build a comprehensive claim package with professional estimates.
From that point on, Our Public Adjusters handles all communication and negotiation with the insurer. You are kept in the loop at every stage, but without the stress of the day-to-day fight.
Take the Next Step on Your Denied Insurance Claim
A denial letter can feel final, but it is often the start of a longer conversation with your insurer. Policies carry strict deadlines, so acting sooner gives you more room to respond. A good first step is gathering your full policy, including the declarations page, along with all communications with your insurance company, photos of the damage, contractor bids, paid invoices, and any engineer reports.
Having these documents organized makes it easier to see where the denial may be challenged and what options are available. Our Public Adjusters can review your situation, explain the process, and handle the inspection, documentation, and communication with your insurer on your behalf.
Call Our Public Adjusters at 832.687.7225 to schedule a free phone consultation about your denied claim.